What happens to a home's "market value" when the market only produces a couple of closings a quarter?
That question is not rhetorical if you are trying to price or finance a house in Alpine. Bergen County's own multiple listing data for March 2026 put the picture in stark terms: 21 active single-family listings in the borough, but only 2 year-to-date sales through that month, against a year-to-date median price of $4.499 million and a March median of $4.0 million. For comparison, Bergen County as a whole posted a year-to-date single-family median of just $800,000 over the same window. Alpine is not simply an expensive corner of the county. It is a market so thin that a handful of closings can move its published median by hundreds of thousands of dollars in either direction, and that thinness changes how appraisals, financing, and pricing strategy actually work here.
Browse Alpine Listings for Sale
A Market Where Every Sale Is Its Own Data Point
Separate portal data from the same spring showed Alpine's March 2026 median sale price at $4.0 million, up 8.8 percent year over year, with a median of $745 per square foot. Another tracker reported 21 homes sold in Alpine in a single month early in 2026, compared with just 2 in the same month a year earlier.
Those numbers are not necessarily in conflict. One is a single month's closings, the other a cumulative quarter, and different trackers define a "sale" and its reporting window differently. But the gap between them is the real lesson. In a town where a full quarter's worth of closings can be counted on one hand, the same three months can look entirely different depending on which source you pull and when you pull it. That is not a flaw in the data. It is what happens when you try to apply median-price thinking, built for markets that trade in dozens or hundreds of homes a month, to a market that trades in single digits.
A comparison across sources makes the point plainly:
Source and window | Headline figure |
|---|---|
Bergen County MLS, year-to-date through March 2026 | $4.499M median, 2 sales |
Bergen County MLS, March 2026 only | $4.0M median |
Portal data, March 2026 | $4.0M median sale price, up 8.8% year over year |
Portal data, single month early 2026 | 21 closings reported |
If you are comparing Alpine to a neighboring town using only the number you saw on one site, you are working with a fraction of the picture.
Why the Appraisal Itself Is the Hard Part
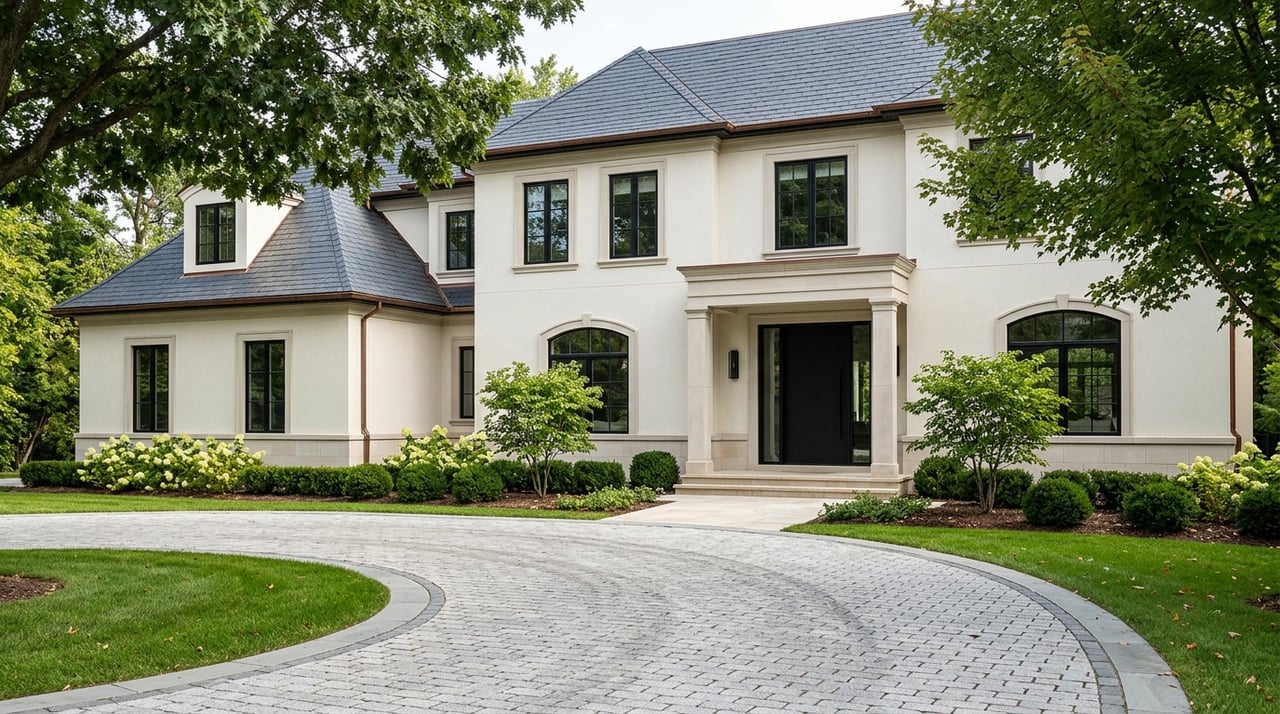
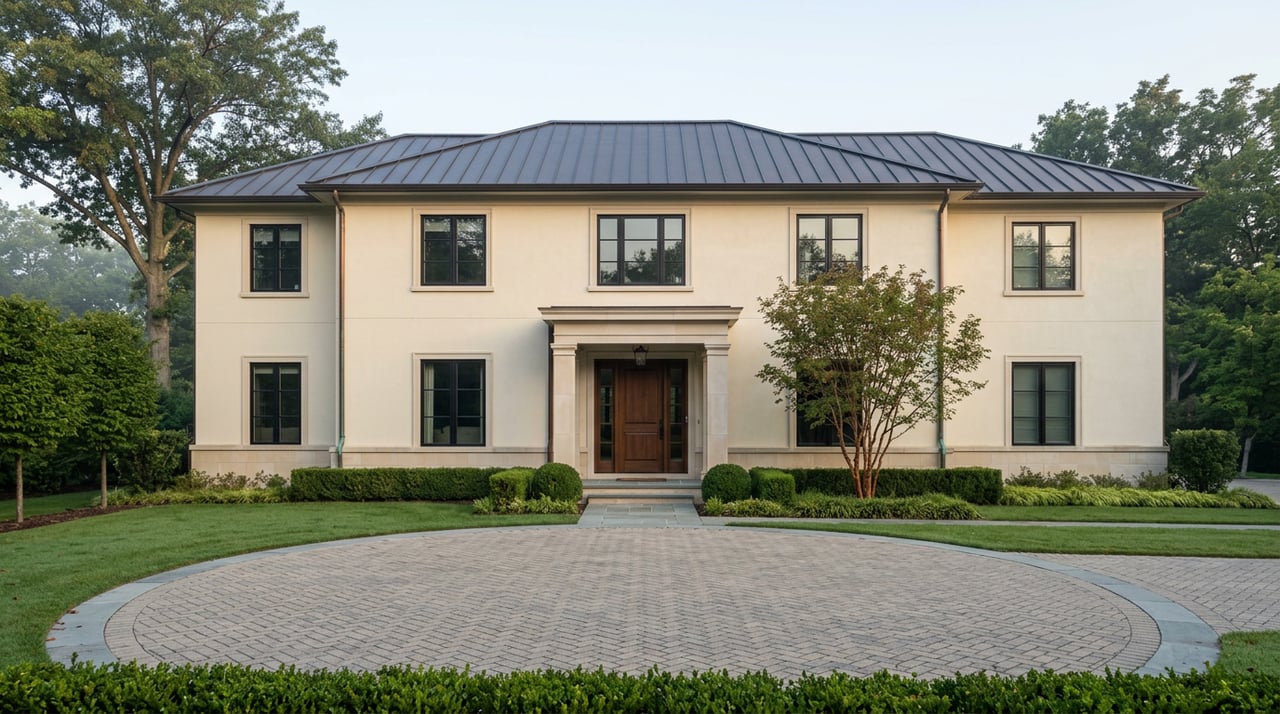
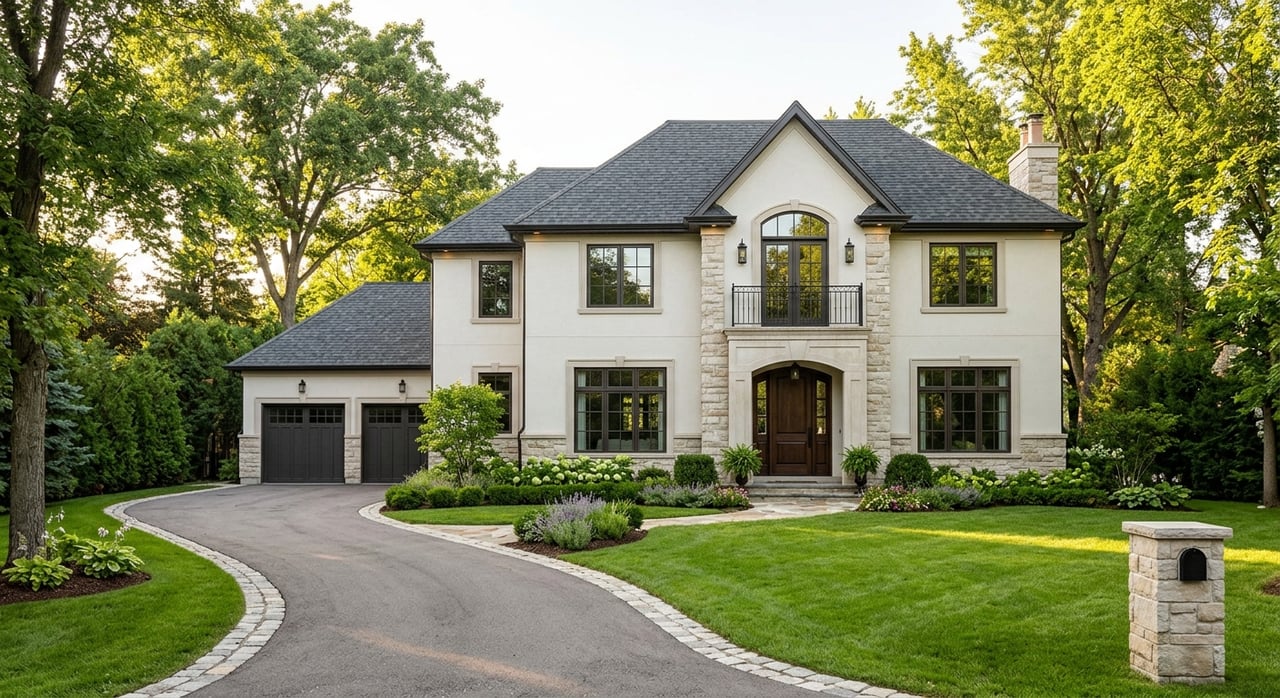
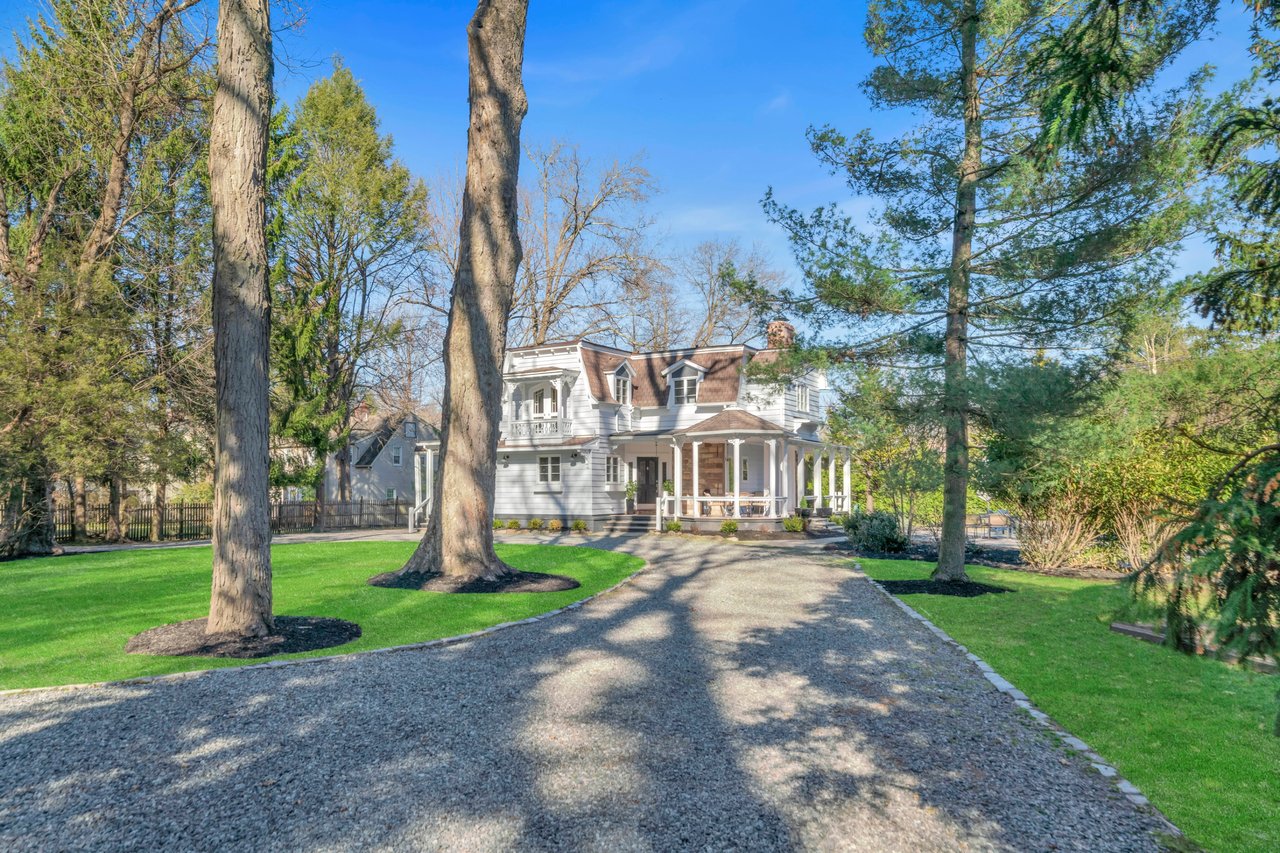
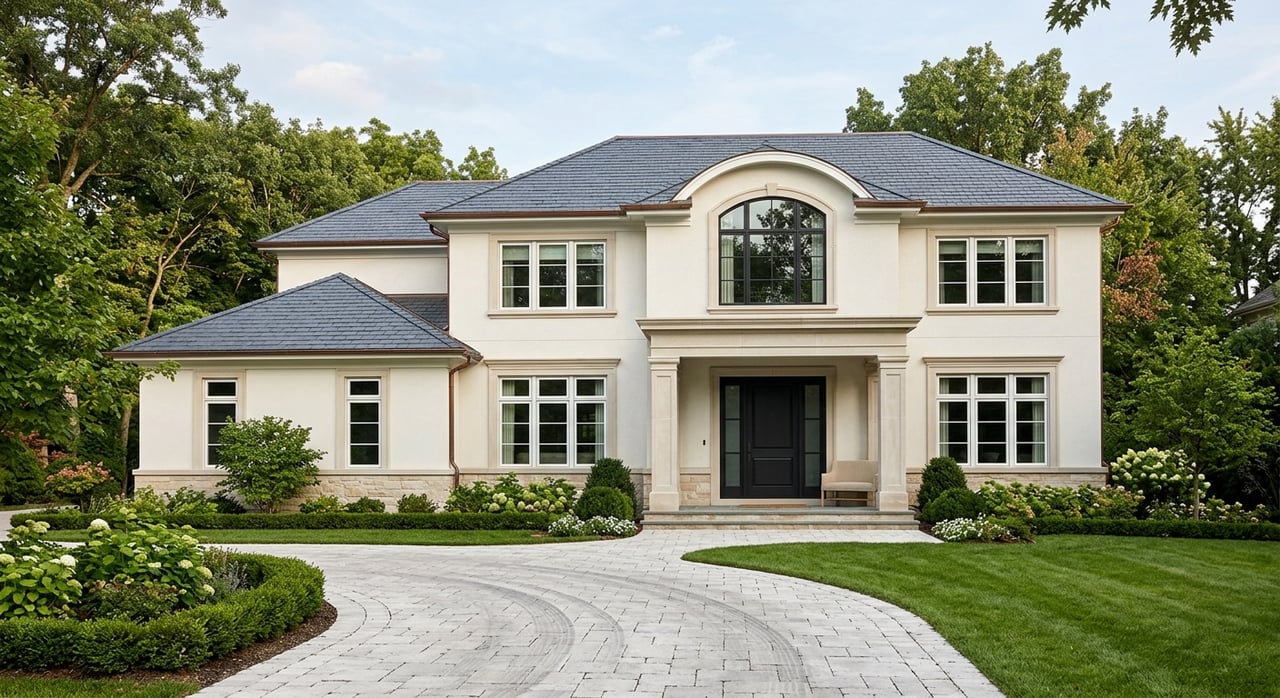
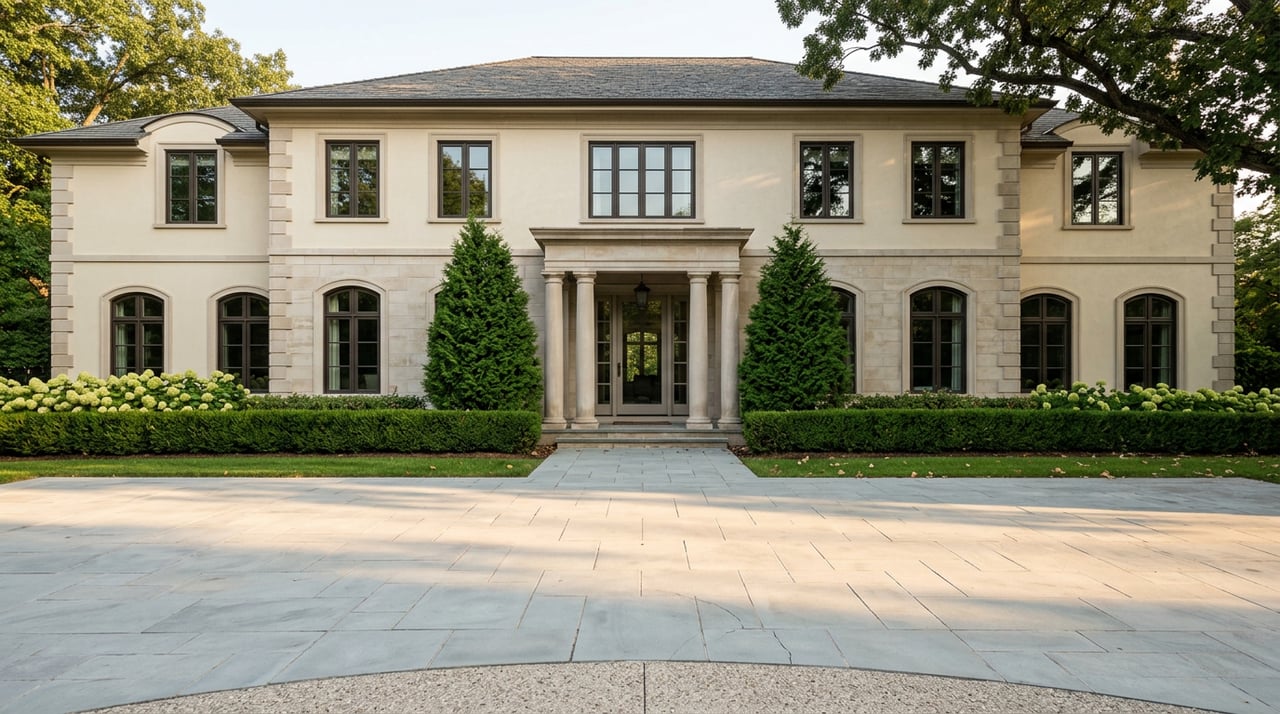
Alpine is one of the highest-priced single-family markets in Bergen County, and it is also a market where housing stock does not repeat itself. Active and recent listings commonly run one to three acres, with architectural styles ranging from French chateau and Georgian Colonial Revival to Tudor and contemporary glass and steel. Two homes on paper-similar lots can diverge sharply in value once you account for gated access, setback, and whether the site actually delivers a clean view corridor toward the Hudson or the Manhattan skyline. Appraisers here are not just comparing square footage. They are pricing absolute privacy—this is, after all, a town so exclusive it famously forgoes direct home mail delivery in favor of the local post office, along with sightlines that do not show up cleanly in a spreadsheet of past sales.
That distinction between list price and closed price matters in a market like this. List data shows where sellers think the market sits and how current inventory is positioned. Closed-sale data shows what a buyer actually paid, adjusted for whatever the property's particular privacy and access profile turned out to be worth to that specific buyer. In Alpine, both figures answer different questions, and neither one alone tells you what your own home, or the home you are bidding on, is likely to appraise for.
The clearest illustration of how far the top of this market can stretch is the 2025 sale of the estate known as Chateau de la Roche, at 48 Rio Vista Drive, which closed at roughly $17.7 million. Reporting from The Real Deal identified it as the highest-priced residential sale recorded on the New Jersey Multiple Listing Service in both 2024 and 2025. That sale sits nowhere near Alpine's published $4.0 million median, and it should not. It is a reminder that in a low-volume luxury market, the "typical" sale and the record sale can coexist in the same handful of annual transactions, and an appraiser working a mid-range Alpine contract has to know which comparable properties actually belong in that conversation and which ones are outliers that will only confuse the number.
The Financing Layer Most Buyers Underestimate
Bergen County sits among New Jersey's high-cost counties for mortgage purposes. For 2026, that means the conforming loan limit for a single-family home tops out at $1,209,750, compared with a baseline limit of $832,750 in the state's standard-cost counties. Given that Alpine's reported medians run from roughly $4.0 million to $4.5 million, nearly every purchase in the borough requires jumbo financing rather than a conventional conforming loan.
Jumbo loans are not purchased by Fannie Mae or Freddie Mac, so lenders hold them on their own books or place them with private investors, which means stricter underwriting. In practice, that shows up as:
- Appraisers working with fewer recent comparable sales, which can extend the appraisal timeline or trigger a desk review in addition to the standard appraisal.
- For very large loan amounts, some lenders requiring two full independent appraisals rather than one.
- Larger down payment expectations, commonly 10 to 20 percent and sometimes higher depending on the lender and the borrower's income profile.
- Meaningful reserve requirements, since many jumbo programs want to see six to twelve months of housing payments in liquid assets, with larger loan amounts sometimes requiring more.
- Extra documentation for buyers whose compensation includes bonuses, RSUs, or other non-salary income, which describes a large share of Alpine's buyer pool given the borough's proximity to New York City.
The practical upshot: if an appraisal comes back below the contract price in a market with this few comparable sales, both buyer and seller need a plan in place before it happens, not after. Waiting to think about appraisal gap coverage until the appraisal is already in hand is the most common way an Alpine deal loses momentum at the worst possible moment.
One Property Type, No Substitutes
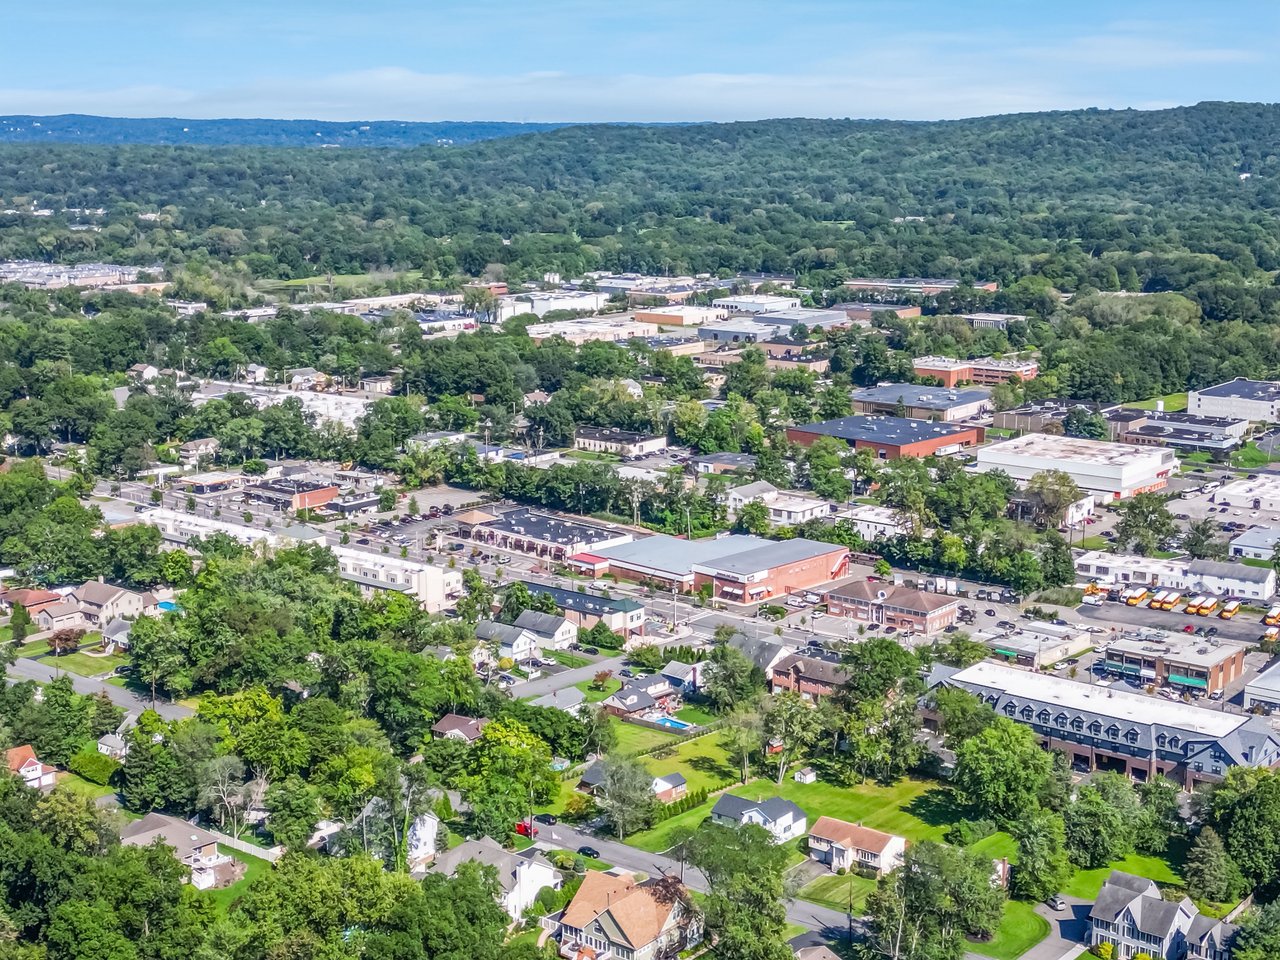
Bergen County's March 2026 report showed no condominium, co-op, or townhouse sales or active listings anywhere in Alpine, and separate portal data reported zero rental inventory for the 07620 ZIP code. That is not a temporary gap in inventory. It reflects what Alpine actually is: a borough built almost entirely around detached single-family estates on substantial lots, with essentially no alternative housing format for a buyer to fall back on if the single-family search stalls.
That has a direct effect on how you should think about competition here. In most Bergen County towns, a buyer priced out of single-family inventory can pivot to a townhouse or condo and stay in the same school system or commute pattern. In Alpine, that pivot does not exist. Borough planning materials also note there is no local mass-transit access, so anyone evaluating the town is already committing to a car-based commute—typically a scenic, direct drive down Route 9W toward the George Washington Bridge Buyers here are not comparing product types. They are deciding whether a specific estate, on a specific lot, with a specific approach and privacy profile, is worth waiting for.
The Tax Line That Changes the Math
For 2025, Alpine's effective property tax rate was 0.794, according to New Jersey Division of Taxation figures, which put it below several nearby Bergen County luxury towns, including Saddle River at an effective rate of 1.030. On a home in the $4 million range, that difference is not trivial. It is the kind of detail that belongs in a carrying-cost comparison before a buyer commits to Alpine over a neighboring town with a similar price point but a meaningfully higher tax rate.
Pricing and Financing With Eyes Open
None of this means Alpine is a hard market to transact in. It means it is a market where the printed number, whether it comes from a portal, an MLS summary, or a neighbor's guess, is the starting point for a conversation rather than the answer. Pricing an Alpine estate correctly means understanding which recent sales are genuine comparables and which are outliers like the Rio Vista record sale. Financing one means building in appraisal gap planning and reserve documentation before you are three weeks into attorney review. Selling one means presenting the privacy and access story clearly enough that an appraiser, not just a buyer, can see the value in it.
In my 14 years navigating the Bergen County luxury market, I’ve learned that an appraiser's local eye matters just as much as the data. I recently had a situation where an out-of-town appraiser undervalued a property because they didn't account for its exceptional privacy and the premium porcelain pavers on the veranda. By calmly walking them through the property and explaining what Alpine buyers actually pay a premium for, we got the valuation exactly where it needed to be.
If you are pricing a sale, evaluating a purchase, or simply trying to make sense of why the numbers you saw online do not match what a neighbor's house closed at, I can help you navigate these unique mechanics. Request a confidential valuation of your Alpine estate or schedule a private consultation to structure your financing strategy with Lana Henriques. Let's talk through what your specific property—or your specific search—actually looks like once you get past the median.
A Few Questions Worth Asking Before You Sign Anything
Does an Alpine purchase always require a jumbo loan? Not always, but in practice, nearly always. With Bergen County's 2026 high-cost conforming limit at $1,209,750 and Alpine's reported medians running from roughly $4.0 million to $4.5 million, most purchases clear that threshold well before financing is finalized.
Why do home value estimates for Alpine vary so much between websites? Because the underlying sample size is so small. A tracker built on automated valuation models will read differently than one built on closed MLS transactions, and a single closing at either end of the price range can shift either figure noticeably. Always check the reporting window and the methodology before comparing two numbers directly.
Is Alpine's property tax rate really lower than other luxury Bergen County towns? For 2025, yes. Alpine's effective rate of 0.794 came in below Saddle River's 1.030, according to New Jersey Division of Taxation data. That is worth factoring into any side-by-side comparison of carrying costs, separate from the purchase price itself.